A VA appraisal in San Diego County currently costs $800 and must be completed within 6 business days of assignment under the VA's published fee schedule, effective May 1, 2026. The VA, not your lender, assigns the appraiser, and the borrower typically pays the fee at closing or upfront. Your first move once you're under contract: ask your lender to confirm the Point of Contact (POC) and appraisal assignment status right away.
TL;DR:
- VA appraisers check safety, structure, and sanitation, not every defect; repairs listed on the Notice of Value generally must be completed before closing.
- For a low value, send comparable sales through your lender within Tidewater’s 2 working day window; request an ROV if the final valuation remains low.
- Condo and HOA paperwork can outlast the appraisal, especially in buildings without prior VA project approval; request those records when the contract is signed.
- The six business day clock starts after assignment, not contract signing, and excludes weekends and federal holidays when calculating the report deadline.
Table of Contents
- VA appraisal fees and timeliness for San Diego: what the numbers mean
- What the VA appraisal inspects: MPRs and the Notice of Value
- How VA assigns appraisers and which appraisal types apply
- If the appraisal comes in low: Tidewater, ROV, and your action checklist
- San Diego timing realities: PCS season, condos, and local bottlenecks
- A local agent's view on keeping VA appraisals on track
- What veterans get wrong about VA appraisals
- How buyer representation helps veterans through the appraisal stage
- FAQ
- Sources
VA appraisal fees and timeliness for San Diego: what the numbers mean
The VA fee schedule sets both the maximum fee an appraiser can charge and how many business days they have to deliver the report once assigned. For San Diego County, that means $800 and 6 business days as of May 1, 2026.
"Business days" in VA terms excludes weekends and federal holidays, and the clock starts the day after assignment, not the day your purchase contract is signed. A Tuesday assignment with no holidays in between typically means a report by the following Wednesday.
| Item | San Diego County detail |
|---|---|
| Appraisal fee | $800 |
| Timeliness requirement | 6 business days |
| Effective date | May 1, 2026 |
| Who pays | Borrower, generally |
| Who assigns | VA, through its appraiser panel |
VA sometimes raises fees or extends timeliness windows temporarily in counties facing heavy appraiser demand, which can affect San Diego during busy stretches. A few questions for your lender help you plan around this:
- Ask when exactly the appraisal was assigned and to whom.
- Request the appraiser's contact information so your agent can coordinate access.
- Confirm the fee amount was authorized and whether it matches the current published rate.
What the VA appraisal inspects: MPRs and the Notice of Value
Every VA appraisal checks a property against Minimum Property Requirements, commonly called MPRs, which exist to confirm a home is safe, structurally sound, and sanitary before a veteran buyer closes on it. These are baseline habitability standards, not a quality checklist.
Common MPR issues in San Diego homes include repairs like quick interior door replacement to fix minor damages during the appraisal process.
- Peeling paint in homes built before 1978, due to lead-based paint rules.
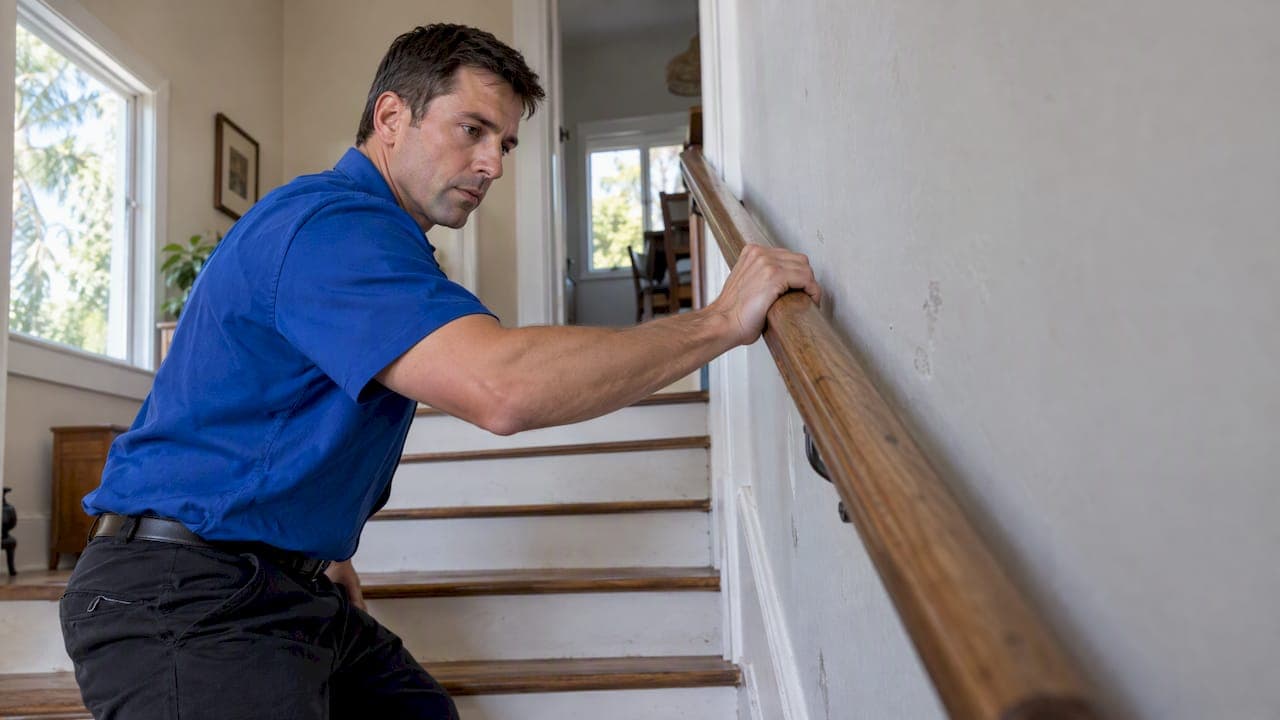
- Missing handrails on stairs or elevated decks.
- Inoperable heating systems, since every VA-financed home needs a working heat source.
- Roof damage that allows water intrusion.
- Exposed wiring or other obvious electrical hazards.
The appraiser documents required repairs on the Notice of Value, or NOV, and those repairs generally must be completed before the loan can close. It's worth being clear about what an appraisal is not: it's not a home inspection. The appraiser is checking for health and safety deficiencies and confirming value, not evaluating every mechanical system or cosmetic flaw the way a licensed inspector would.
Pro Tip: When an MPR repair surfaces, ask your agent to request a seller credit or repair completion in the counteroffer rather than renegotiating the full purchase price, since most MPR items cost far less to fix than they seem.
How VA assigns appraisers and which appraisal types apply
VA fee panel appraisers operate as independent contractors, and the assignment process is designed so lenders can't select or steer who gets your file, which keeps the valuation objective. Depending on circumstances, your appraisal may take one of a few forms:
- Interior appraisal, the standard full inspection of the home's interior and exterior, used for most purchase transactions.
- Exterior-only appraisal, permitted under specific conditions outlined in VA Circular 26-22-13, often for refinances rather than new purchases.
- Desktop appraisal, completed without a site visit using available data, allowed under the same circular's Alternative Appraisal Processing Program (AAPP) framework.
That circular also describes an assignment "waterfall": when a case goes unassigned for more than 7 business days, typically because local panel appraisers are stretched thin, VA widens the pool or reassigns to keep the file moving. Lenders participating in VA's Lender Appraisal Processing Program (LAPP) can also manage parts of this process directly, which can shave time off larger metro areas like San Diego.
Be ready to provide access instructions, lockbox codes, or a reliable point of contact quickly once assignment happens, since delays in scheduling access are one of the most common self-inflicted holdups in the process.
If the appraisal comes in low: Tidewater, ROV, and your action checklist
If an appraiser believes the home will value below the contract price, VA's Tidewater process requires notifying your lender's POC before finalizing the report, giving you a narrow 2-working-day window to submit additional sales data under VA Circular 26-17-18. Missing that window doesn't end your options, but it does close the easiest one.
If the NOV still comes back low, a formal Reconsideration of Value (ROV) is the next step. Appraisers are generally expected to respond within 5 working days when supporting data is submitted in the same comparable-grid format they use on the Uniform Residential Appraisal Report.
- Pull verifiable, recently closed comps your agent believes the appraiser may have missed.
- Format them like a URAR grid, the same layout the appraiser's report uses, since this format gets taken most seriously.
- Have your lender's POC officially log the Tidewater or ROV request.
- Submit everything through the lender, not directly to the appraiser.
- Track the appraiser's response window and follow up through your lender if it lapses.
Pro Tip: The sooner you deliver comps, ideally within that initial 2-day Tidewater window, the more likely the appraiser folds them in without adding real delay to your closing.
Appraisers can sometimes charge an additional fee for ROV work; if you hit resistance, your lender can escalate through the Regional Loan Center handling your file.
San Diego timing realities: PCS season, condos, and local bottlenecks
San Diego's VA appraiser panel is relatively deep, and most buyers see turn times in the range local lenders commonly report, though this shifts with demand. PCS season, roughly May through August, brings a wave of military relocations that stretches appraiser availability and can push turnaround toward the longer end of what's typical.
A few friction points show up repeatedly in San Diego transactions:
- Condo and HOA document requests can take longer to process than the appraisal itself, especially in buildings without a VA-approved project history.
- Coastal properties sometimes face insurability questions that complicate underwriting timelines.
- Older or unusual property types, common in neighborhoods like North Park or Point Loma, can require more appraiser research time.
Requesting condo HOA documents the day you go under contract, flagging obvious MPR issues before the appraiser arrives, and giving one clear point of contact all shave real days off a San Diego closing timeline.
A local agent's view on keeping VA appraisals on track
Managing a VA appraisal in San Diego comes down to removing friction before it starts. That means entering the POC with the lender immediately after contract acceptance, pulling comparable sales in URAR format in case an ROV becomes necessary, and getting ahead of minor repairs, like a loose handrail or a dated smoke detector, before the appraiser ever walks through. For condo purchases, chasing down HOA paperwork early is often the single biggest time saver, since those documents can take longer to arrive than the appraisal itself.

What veterans get wrong about VA appraisals
The most common misconception is that a low appraisal ends a deal. It doesn't, it starts a negotiation with specific, VA-defined tools attached to it: Tidewater, then ROV, both with real response windows an appraiser is expected to honor. Veterans who treat the appraisal as a fixed verdict lose leverage they actually have.
The conventional advice, "just wait and see what the appraiser says," undersells how much a well-prepared buyer's agent can influence outcomes before the Tidewater window even opens. Comps delivered early, in the right format, change outcomes more often than people expect.
What matters most is sequencing: confirm your POC the day you're under contract, flag MPR issues before the appraiser's visit, and have your comps ready before you need them, not after a low number arrives. Veterans who prioritize that order tend to close on time and with far less stress than those who react after the fact.
— Jeff
How buyer representation helps veterans through the appraisal stage
We work directly with veterans and active military buyers, and the appraisal stage is exactly where hands-on coordination pays off. Through Buy With Confidence, we manage POC communication with your lender, prepare comparable sales in the format appraisers actually use, and flag likely MPR issues before they become closing delays.
If you're still house hunting, a Home Valuation gives you a realistic read on local pricing before you write an offer, which matters when you're trying to avoid appraisal gaps from the start. For buyers who want a more concierge-level search, including off-market options, our VIP Home Search service is built for exactly that. Reach out whenever you're ready to talk through your timeline.
FAQ
What is the average cost of a VA appraisal in San Diego?
The VA appraisal fee for a single-family home in San Diego County is $800 as of May 1, 2026. This fee is set by VA's published schedule and is generally paid by the borrower.
How do I get a VA appraisal in San Diego?
Your lender orders the appraisal once your purchase contract is signed, and VA assigns the appraiser from its panel, not the lender. Your job is to confirm the assignment date and POC with your lender right away so your agent can coordinate access.
How hard is it to pass a VA appraisal?
Most homes pass without major issues, since VA appraisers are checking for basic safety, structural, and sanitary standards called MPRs, not every cosmetic flaw. Common fail points, like missing handrails or inoperable heating, are usually inexpensive to resolve before closing.
What is the VA appraisal fee schedule for 2026?
As of May 1, 2026, the VA fee schedule lists an $800 fee for San Diego County with a 6 business day timeliness requirement. Fees and timeliness vary by county and can be adjusted temporarily in high-demand markets.
What happens if my VA appraisal comes in low?
VA's Tidewater process lets you submit additional comparable sales within 2 working days before the Notice of Value is finalized. If the value still comes in low, a Reconsideration of Value request, submitted through your lender with comps in URAR format, is the next step.