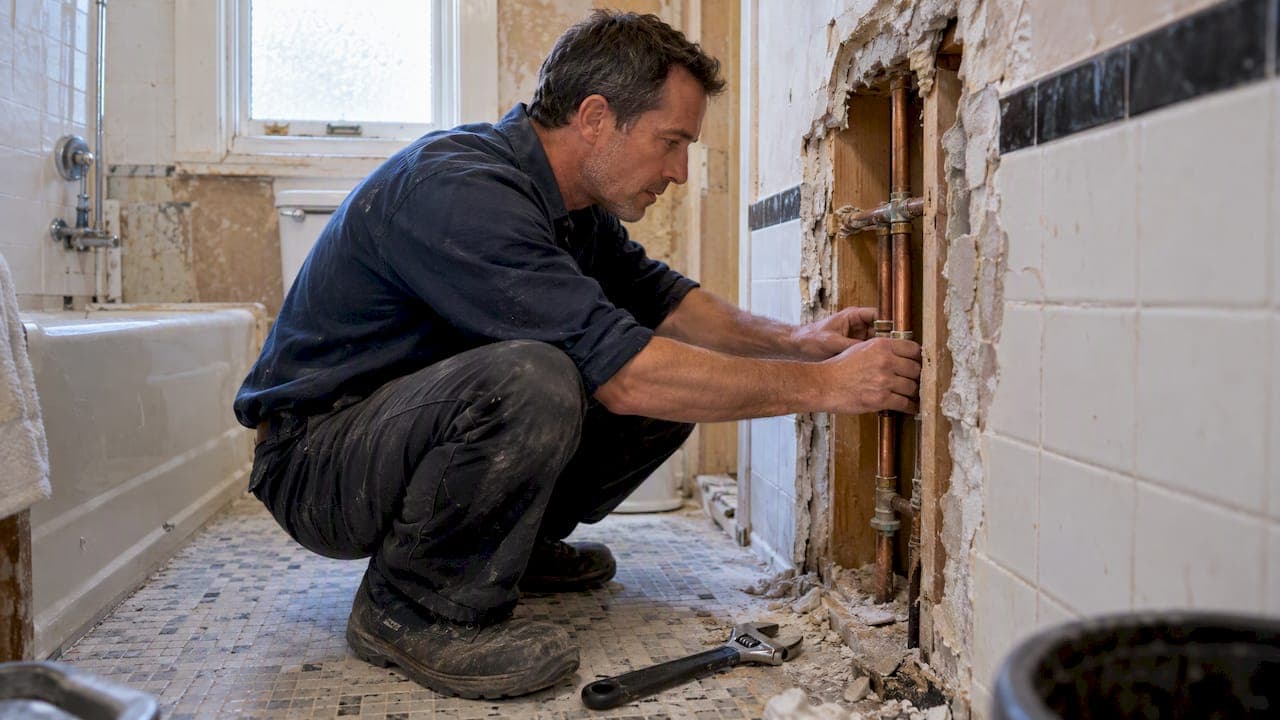
Plan on San Diego renovation costs running about 35% above the national baseline, and set aside a 10–25% contingency on top of your bids. Even permitting is a real line item: City of San Diego inspection fees for a standard single-dwelling remodel start at $3,275.45 before any other charges.
TL;DR:
- A midrange kitchen typically costs $48,000 to $85,000, while remodels of entire homes run $100,000 to $500,000; finishes and layout changes drive the spread.
- City plan check and administrative fees are separate from inspection charges, due before review, and nonrefundable if a project stalls.
- Standard FHA 203(k) financing covers major structural work without a renovation cap but requires an approved consultant; Limited 203(k) covers nonstructural repairs up to $35,000.
- Inspect aging systems and obtain two or three itemized bids before removing contingencies; ask contractors to separate labor, materials, permits, and code compliance.
- Coastal lots may need extra review, and FHA 203(k) borrowers must secure permits before work begins, so approval timing can affect the purchase schedule.
Table of Contents
- What do fixer upper costs in San Diego look like by project?
- Why do San Diego renovation bids run higher than the national average?
- How do permits and plan-check fees affect a San Diego fixer-upper budget?
- How can you finance a fixer-upper with an FHA 203(k) loan?
- What should your fixer-upper budgeting checklist include?
- How do you estimate renovation costs for one specific property?
- What does a San Diego buyer's agent see that buyers miss?
- How can we help you buy a San Diego fixer-upper?
- FAQ
- Sources
What do fixer upper costs in San Diego look like by project?
San Diego fixer upper costs depend heavily on scope, but a few project types drive most budgets. Local guides such as RemodelerIQ's San Diego cost guide and Cost to Renovate publish ranges that already reflect the local premium, which is why they run well above national figures.
| Project | Typical San Diego range |
|---|---|
| Mid-range kitchen remodel | $48,000–$85,000 |
| Full bathroom remodel | Varies by scope and finish level |
| Roof replacement | Varies by roof size, materials and condition |
| Whole-house remodel | $100,000–$500,000 |
Other projects you may price on a fixer-upper, such as an accessory dwelling unit (ADU) or a deck and landscape refresh, vary too widely by lot and design for a single honest range. Ask for written bids rather than trusting a generic number.
Finish level moves these numbers more than almost anything else. A low-end finish uses stock cabinets, laminate or basic tile, and keeps existing layouts. A mid-range finish adds semi-custom cabinetry, quartz counters, and some layout changes. A high-end finish brings custom millwork, premium appliances, and structural changes, and it is where whole-house projects climb toward the top of their range.
Here is how that works in a simple, illustrative case. Say you buy a dated house and plan a mid-range kitchen, a bathroom remodel and a roof replacement. The combined cost before soft costs and contingency can add up quickly. These inputs are examples only, not market data, but they show how quickly common projects stack up.
Keep these points in mind when you use the table:
- Ranges are starting points, not quotes. Your property's age, access and condition move the final figure.
- Roofing is the widest range, so get a roofer on site early. A local option like Smart Roofing & Restoration publishes pricing and handles coastal conditions that affect material choice.
- Smaller upgrades can save money and disruption. Interior door and closet replacement through a dealer like One Day Doors & Closets is a lower-mess alternative to a full carpentry job.
- Local guides put the San Diego premium roughly 32–42% above national averages, so never plug a national estimate into a local budget.
Why do San Diego renovation bids run higher than the national average?
Several local forces stack on top of base material prices, and understanding them helps you judge whether a bid is reasonable or padded.
- Coastal review. Coastal-zone permitting can add costs to some projects. Check with the City about requirements for the property.
- Permitting overhead. Plan check, inspection and agency fees are covered in the next section, but they are a built-in cost of doing legal work here.
RemodelerIQ applies a regional cost factor of about +35% for San Diego versus the national baseline, and that single multiplier explains much of the gap between a generic online estimate and a local bid. (RemodelerIQ)
If a contractor's number looks high, ask which code-driven items are inside it. A line for Title 24 compliance is normal. A vague lump sum with no breakdown deserves a follow-up question.
How do permits and plan-check fees affect a San Diego fixer-upper budget?
Permits are one of the few fixer-upper costs you can look up in advance. The City of San Diego publishes its fee schedules in information bulletins, and Bulletin 103 shows that building permit inspection fees for a standard single-dwelling addition or remodel up to 500 square feet start at $3,275.45. Separate mechanical, electrical or plumbing permits add to that depending on scope.
Plan check fees are a separate charge. Bulletin 501 lists the plan check and inspection fee tables and warns that plan check and other administrative fees are nonrefundable, so a project that stalls after submittal still costs you. The City's residential addition and remodel guidance also says plan check fees are due before review begins.
Here is what to build into your numbers:
- The base permit and inspection fee for your scope, taken from the current City schedule.
- Plan check fees, which you pay up front and cannot get back.
- Separate mechanical, electrical and plumbing permits if those systems are touched.
- Additional agency charges, such as water and sewer plan checks or a Coastal Development Permit where they apply.
- Review time. Each approval step adds weeks, and your contractor cannot start permitted work until the permit is issued.
Final fees are confirmed during review and can change, so treat any published figure as an estimate.
Pro Tip: Contact the City's Development Services Department early, ideally during your inspection period, and write the fee and review time into your purchase and move-in schedule.
How can you finance a fixer-upper with an FHA 203(k) loan?
The FHA 203(k) program is one way to roll the purchase price and renovation costs into one loan. According to HUD's consumer fact sheet_Consumer_FS_English.pdf), there are two versions:
- Standard 203(k): Allows major structural work with no maximum renovation amount and requires an FHA-approved 203(k) consultant.
- Limited 203(k): Covers non-structural repairs up to $35,000 and may not require a consultant.
Under either version, permits must be obtained before work begins. That sequencing matters in San Diego, where permit timelines can stretch your closing-to-construction schedule. Talk to a 203(k)-experienced lender before you write an offer so your timeline and your loan match.
Other options exist, each with a tradeoff:
- A larger mortgage with cash reserved for repairs. Simple, but it ties up cash and may require a bigger down payment.
- A home equity line of credit (HELOC). Flexible draws, but you need existing equity, and rates can move.
- A home improvement loan. Fast and unsecured in many cases, but rates are often higher and terms shorter.
SoFi's fixer-upper guidance notes that the right choice depends on the borrower, so compare total cost and timing rather than headline rates.
What should your fixer-upper budgeting checklist include?
Turn a rough range into a real budget with these steps, in this order:
- Complete the home inspection and any specialty reports the property needs.
- Collect itemized written bids from two or three licensed contractors.
- Confirm which parts of the scope trigger permits.
- Add soft costs: permits, inspections, design fees, temporary housing and utility upgrades.
- Add a contingency of 10–25% of the total.
- Build a realistic schedule that includes permit review time.
SoFi's guidance recommends that 10–25% contingency because renovation costs often exceed first estimates and timelines extend. Choose the higher end when the house is older, when structural work is involved, or when you cannot see the condition of major systems like plumbing, electrical and the roof. A newer house with a cosmetic scope can sit near the low end.
Common big-ticket surprises include structural repairs, plumbing and electrical updates, and roof replacement, which is why those items belong in your inspection scope before you commit.

Pro Tip: Ask each contractor to break out Title 24 or other special-code compliance items on their bid so you can see exactly which costs are code-driven.
How do you estimate renovation costs for one specific property?
General ranges get you to a ballpark. This workflow gets you to a number you can bring to a lender:
- Order a full home inspection, plus targeted reports where the house calls for them, such as a sewer scope, roof drone photos or a termite report.
- Get at least two or three itemized written bids that separate labor, materials and permit or soft costs, so you can compare like with like.
- Check which City permit triggers apply, and whether coastal or geotechnical reviews affect the lot. Add those fees and the added time.
- Map your contractor's schedule against your lender's draw and timing requirements, then fit both into your purchase timeline.
- Compare the finished budget against likely post-renovation value. Our price per square foot guide helps with that step, and our home buying and selling guide for 2026 covers the broader process timing.
What does a San Diego buyer's agent see that buyers miss?
Most buyers budget for the kitchen and bath they can see and underbudget what they cannot. In our experience helping San Diego buyers, the surprises are usually aging systems, code-driven items that come with any permitted work, and coastal review on lots that look straightforward. The best defense is order inspections early, get contractors into the house before you remove contingencies, and talk to your lender about timing before you write the offer. A good agent coordinates all of that so you are not making a major financial decision on a guess. Remember that any real budget requires an inspection and written bids, and nothing in an article replaces them.
— Jeff
How can we help you buy a San Diego fixer-upper?
If you are weighing a fixer-upper, we help you test the numbers before you commit. With our Buy With Confidence service, we provide personalized support as you consider a San Diego home purchase. Our VIP Home Search helps you search for properties, and our Home Valuation provides a home valuation. When you are ready to talk through a specific house, start on our buyer page.
FAQ
Can you live in a fixer-upper house?
Often yes, but it depends on the scope. Cosmetic work usually lets you stay, while kitchen, bath or structural projects may force you out for weeks. Budget for temporary housing if utilities or key rooms will be offline.
Is it cheaper to build or buy a house?
For a San Diego fixer upper, buying and renovating is often cheaper than building new, but not always. Land, permits and local labor costs apply either way. Compare a full written renovation bid against a build estimate before deciding.
What is the average cost to renovate a house in San Diego?
There is no single average because scope varies so much. Whole-house remodels commonly run $100,000 to $500,000 depending on scope and finish level. Itemized bids on your specific property give the only reliable number.
How much contingency should you budget for a fixer-upper?
Plan for 10–25% on top of your bids. Go higher for older homes, structural work or unknown systems.
Sources
- Fee Schedule for Mechanical, Electrical, Plumbing/Gas Permits | City of San Diego Official Website
- 2026 Remodeling Cost Guides for San Diego, CA | RemodelerIQ
- The Cost of Buying a Fixer-Upper | SoFi